

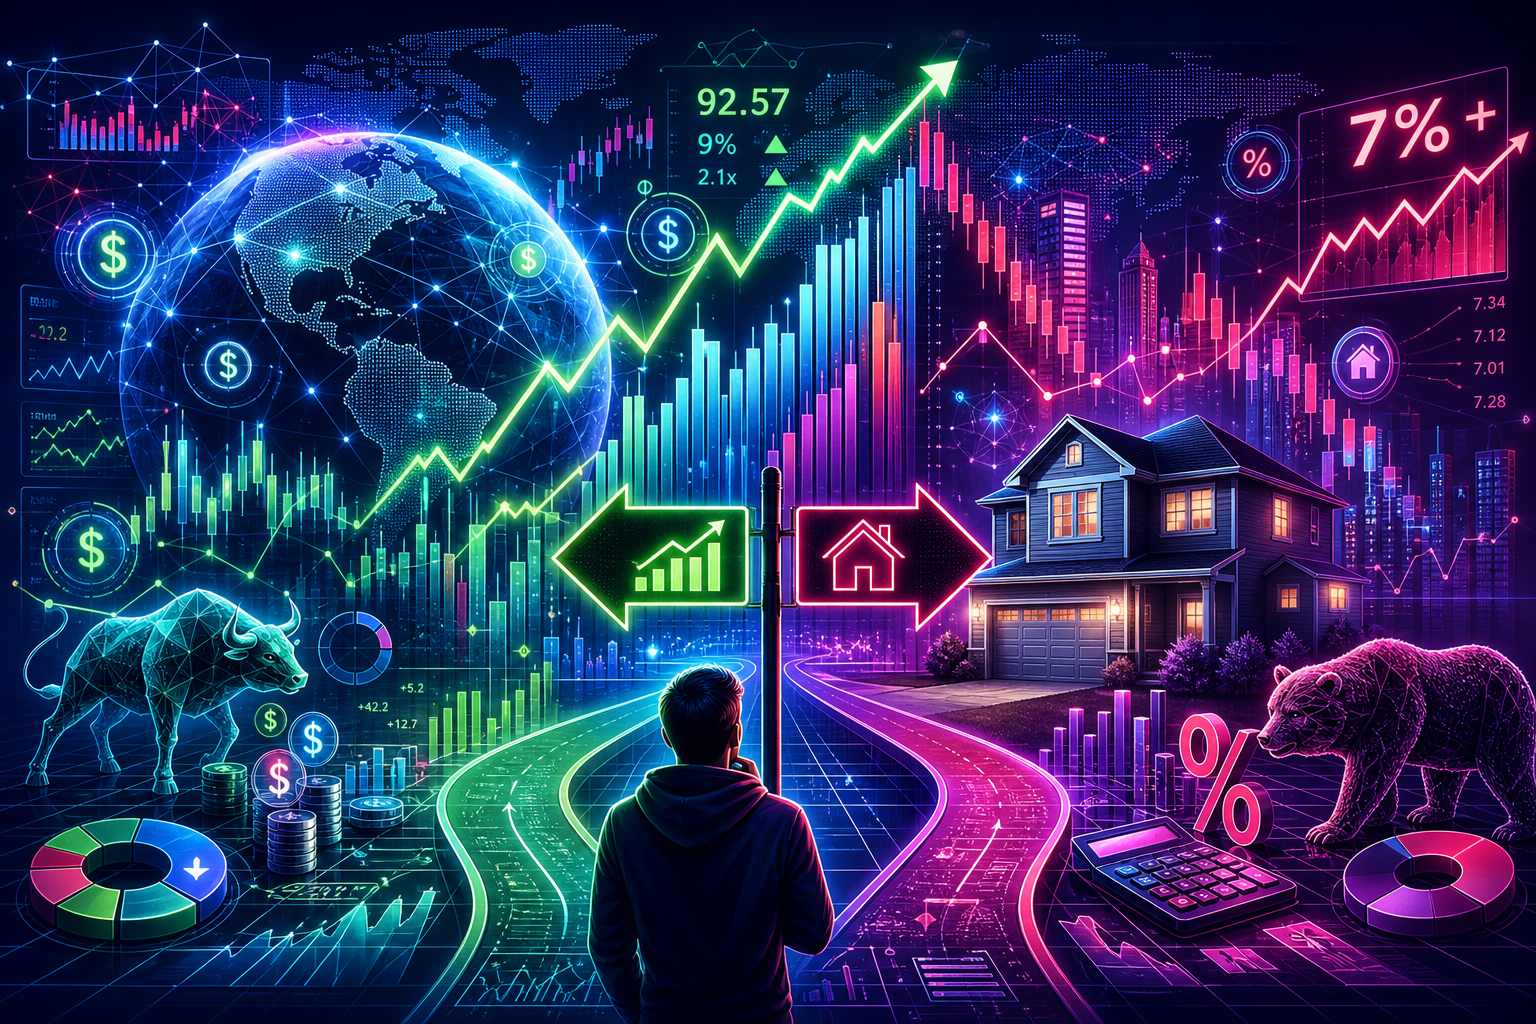
In recent years, the U.S. housing market has faced significant challenges, particularly as mortgage rates surge above 7%. This development has prompted many to reconsider their traditional view of homeownership as a cornerstone of wealth building. The stark contrast between the performance of the stock market, particularly the S&P 500, and the housing market over the past decade has further fueled this trend.
The Current Landscape: Mortgage Rates and Market Performance
The Federal Reserve's aggressive rate-hiking campaign, initiated in 2022, was designed to combat rising inflation. This tightening of monetary policy has had a profound impact on mortgage rates, which have now exceeded the 7% mark for 30-year fixed mortgages. For many potential homebuyers, this has effectively frozen the housing market, making homeownership seem less attainable than ever.
In contrast, the stock market, particularly driven by advancements in artificial intelligence (AI), has seen an unprecedented boom. The S&P 500 has enjoyed double-digit annual gains reminiscent of the late 1990s dot-com era. From December 2015 to December 2025, the S&P 500 has skyrocketed by an astonishing 235%, a stark contrast to the 87% increase in home prices as measured by the Case-Shiller Index.
Younger Generations Shift Focus: Renting vs. Buying
For younger Americans who find themselves increasingly locked out of the housing market, the choice is becoming clear: rent and invest in stocks instead. The financial landscape has shifted dramatically, and many millennials and Generation Z members are prioritizing investments in equities over saving for a down payment on a home. From a financial perspective, this strategy has proven beneficial over the past decade.
This generational shift reflects a broader reevaluation of what it means to achieve financial stability. As Ray Fisman, an economist at Boston University, and Michael Luca, an economist at Carnegie Mellon University, noted in a recent op-ed for The Wall Street Journal, the traditional rent-versus-buy decision involves trade-offs that are often overlooked.
Rethinking Homeownership: A Bundled Decision
Fisman and Luca emphasize that the decision to buy a home is not just about where to live; it also encompasses how to invest a significant portion of one’s life savings. This duality complicates the analysis of whether homeownership is a sound investment. While owning a home provides a place to live, it also represents a considerable financial commitment.
Key Points to Consider: - Investment Returns: Although home prices have increased, the returns on investment can be lackluster. Even during a period of rising home values, buyers often experience "meh" returns. - Market Dynamics: In 2026, for instance, home prices have only risen by 1.5% nationwide, while the S&P 500 has surged by 13%. Such disparities raise questions about the attractiveness of homeownership as an investment. - Borrowing Dynamics: The ability to finance a home purchase can distort perceptions of investment gains. With a typical down payment of 20%, a 10% increase in home value can translate to a 50% return on initial equity. Conversely, a decline in prices can severely impact homeowners, particularly since real estate is a single, illiquid, and undiversified asset.
The Buyer’s Market: A Silver Lining
Despite the challenges posed by rising mortgage rates, there are indications that the current housing market favors buyers. Recent reports indicate that sellers are increasingly willing to offer concessions to attract buyers. In August, concessions were made in 44.7% of home sales, the highest level seen since 2020, according to Redfin.
Common Concessions Include: - Mortgage Rate Buy-Downs: Sellers may offer to lower the buyer's mortgage interest rate. - Home Repairs: Agreements to cover repair costs can be attractive to buyers. - Incentives: Some sellers are going above and beyond to entice buyers, offering household appliances or even vacations and cruises as part of the sale.
As Redfin Chief Economist Daryl Fairweather explains, these concessions indicate that home prices are declining, allowing buyers to secure better deals. For instance, one real estate agent in Atlanta even offered a week-long vacation in an Airbnb owned by the seller to close a deal.
The Financial Advisor's Perspective: Balancing Risks and Rewards
Financial advisors often caution against the risks associated with leveraging debt to purchase a single asset, whether that be a home or a stock. Fisman and Luca highlight that the tendency to conflate the choices of where to live and where to invest can lead to significant financial missteps.
While homeownership has its benefits—such as the freedom to remodel without a landlord's permission—renting can provide flexibility in a volatile housing market. The decision should be made based on individual financial situations and long-term goals.
Benefits of Renting: - Flexibility: Renting allows for easier relocation, especially important for those in job transition. - Lower Upfront Costs: Renters avoid the hefty down payments associated with home purchases. - Investment Opportunities: Funds that would be tied up in a down payment can be used to invest in other assets.
Broader Implications: A Cultural Shift in Wealth Building
The ongoing shift towards investing in the stock market over homeownership is not simply a financial decision; it reflects a cultural change in how younger generations view wealth-building. As economic conditions evolve and the traditional pathways to financial stability become more complex, many are redefining success outside the framework of owning a home.
This paradigm shift may have long-term implications for the housing market and financial sectors. If the trend continues, we may see: - Increased Demand for Rentals: As more young people opt for renting, demand for rental properties may increase, driving up rental prices. - Focus on Alternative Investments: Young investors may explore other investment opportunities, such as cryptocurrencies or emerging markets, rather than traditional assets like real estate. - Changes in Homeownership Rates: A decline in homeownership rates could reshape public policy and housing market strategies.
Conclusion: A New Investment Paradigm
As the landscape of investing evolves, the choice between homeownership and stock market investment is increasingly complex and nuanced. With rising mortgage rates and an uncertain housing market, many younger Americans are turning their backs on traditional paths to wealth in favor of stock market investments that have proven more lucrative over the past decade.
While homeownership remains a cherished goal for many, it's essential to recognize that the decision involves more than just finances. Balancing the desire for a stable living environment with investment opportunities requires thoughtful consideration of individual circumstances. As Fisman and Luca aptly summarize, potential homeowners must disentangle the intertwined decisions of where to live and how to invest, paving the way for a more informed approach to wealth-building in today’s financial landscape.
No comments yet. Be the first to share your thoughts!