

TITLE: The Unraveling of Crypto Privacy Regulations: A Tale of Two Administrations
SUMMARY: The Trump administration's proposed crypto privacy regulations, initially introduced in late 2020, faced intense scrutiny and pushback, leading to their eventual withdrawal under his second administration. This article delves into the implications of this regulatory rollercoaster, examining the ongoing debate over privacy in cryptocurrency and the challenges regulators face in balancing security with individual rights.
The Crypto Regulation Tug-of-War: A Historical Perspective
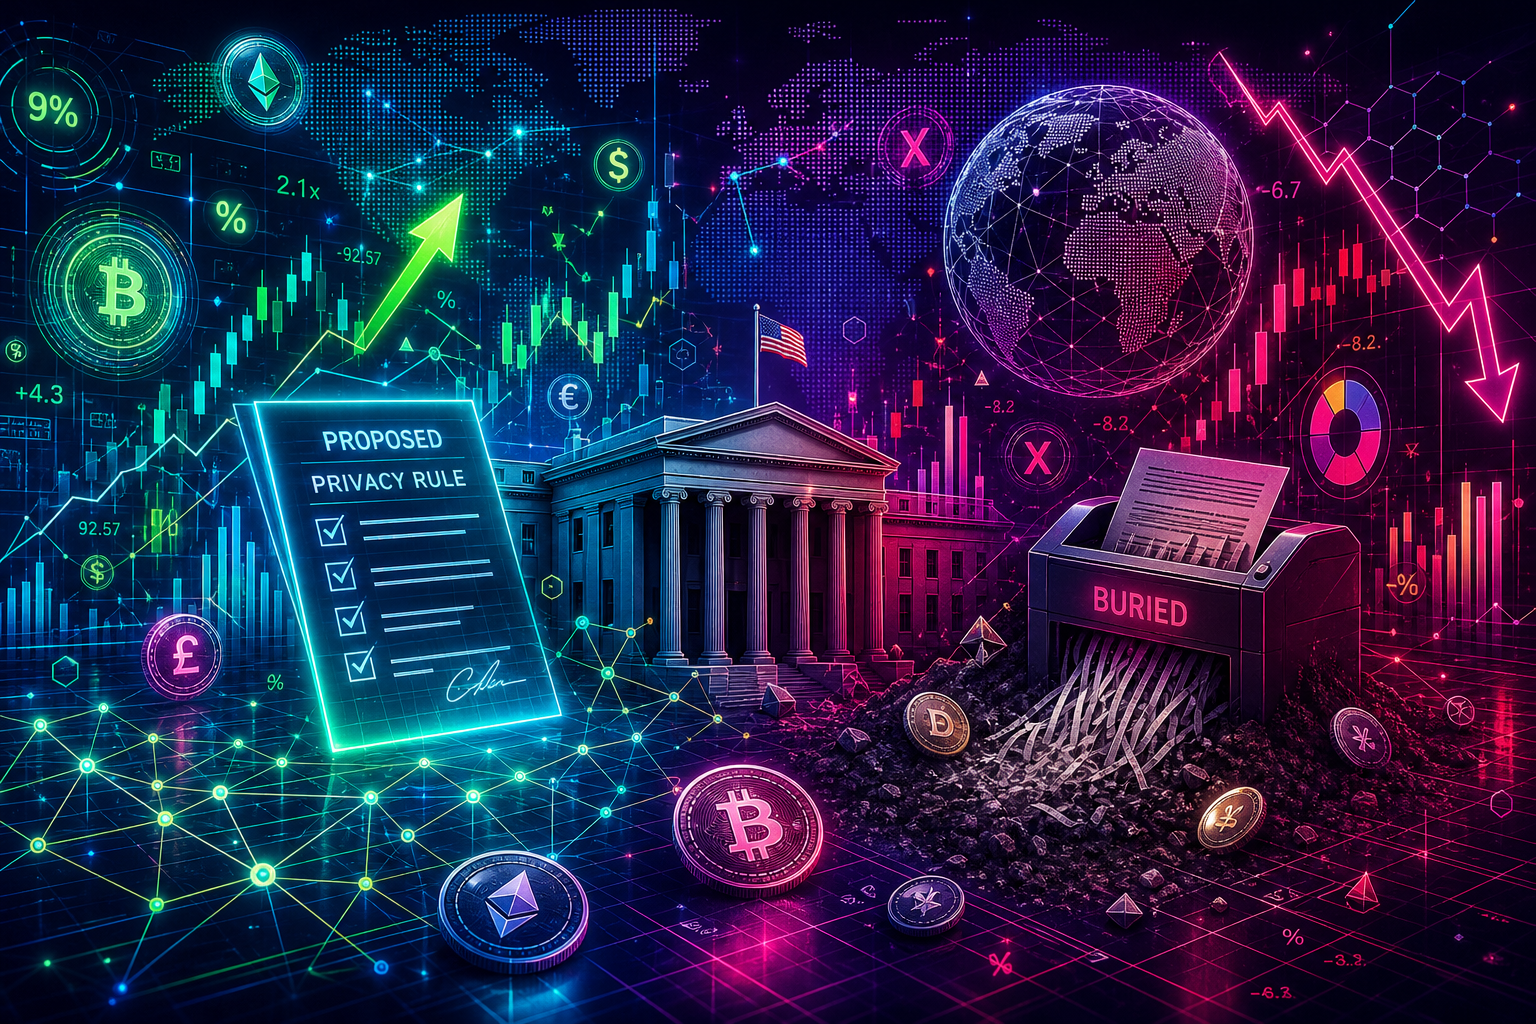
In December 2020, just weeks before Donald Trump was set to leave the White House, his Treasury Secretary, Steven Mnuchin, unveiled a controversial proposal aimed at increasing scrutiny over cryptocurrency transactions. This initiative, which sought to impose stringent reporting requirements on financial institutions dealing with “unhosted wallets,” sparked a fierce debate over privacy and regulatory oversight in the crypto space. Fast forward to 2023, and the same proposal was quietly withdrawn, marking a significant shift in the regulatory landscape that raises questions about the future of crypto oversight and personal privacy.
The Proposed Regulations: What Were They?
The rule put forth by Mnuchin's Treasury Department required crypto exchanges and financial institutions to gather extensive information on transactions involving wallets that users controlled themselves, often referred to as “self-custody” wallets. The urgency of this proposal was framed around national security concerns, with officials claiming that the growing use of cryptocurrencies in illicit activities necessitated immediate action.
Key elements of the proposal included:
- Reporting Requirements: Transactions exceeding $10,000 would require financial institutions to report detailed information about the parties involved, including names and addresses.
- Recordkeeping Obligations: Additional requirements for transactions over $3,000, focusing on identity verification of counterparties.
- Limitations on Self-Custody: While the proposal did not outright ban self-custody, it placed the onus on regulated entities to collect and report personal information, effectively extending banking rules into the realm of cryptocurrency.
The Rationale Behind the Proposal
The Treasury's justification for these proposed rules hinged on the argument that unregulated cryptocurrency transactions posed significant risks for financial crime, including money laundering and terrorism financing. Mnuchin specifically pointed to transactions associated with North Korean cybercriminals as a catalyst for these regulatory changes. The perception was clear: as cryptocurrencies gained traction, so too did their potential misuse.
However, the proposal encountered immediate backlash from privacy advocates, who argued that the measures were unnecessarily invasive and would undermine the fundamental principles of decentralized finance. Critics contended that requiring financial institutions to gather personal information about individuals engaging in peer-to-peer transactions was a disproportionate response that could chill innovation and infringe upon privacy rights.
The Fallout: Public Response and Delays
Upon its announcement, the proposal was met with a barrage of criticism. Advocates for cryptocurrency, such as the nonprofit Coin Center, raised concerns over the expedited comment period, which allowed barely two weeks for stakeholders to respond—most of which fell during the holiday season. This rushed timeline led to many voices in the crypto community feeling sidelined in a significant regulatory process.
In response to the overwhelming feedback, FinCEN extended the comment period but failed to produce any concrete outcomes during the Biden administration, which took office shortly after the proposal was introduced. The transition of power brought with it a shift in priorities, and the proposed regulations languished in the bureaucratic pipeline.
The Biden Administration's Stance
Under President Biden, the focus on cryptocurrency regulations shifted. The administration did not prioritize the withdrawal of the proposed rule but allowed it to stall indefinitely. By the spring of 2024, the proposal was officially marked as "withdrawn," indicating a complete cessation of regulatory action as the government sought to reevaluate its approach to cryptocurrency oversight.
This withdrawal not only marked the end of a contentious regulatory proposal but also reflected the challenges faced by policymakers in navigating the rapidly evolving landscape of digital currencies. The Biden administration's more cautious approach emphasized the need for a balanced regulatory framework that addressed security concerns without stifling innovation.
The Broader Implications of the Regulatory Withdrawal
The withdrawal of the proposed regulations raises essential questions about the future of cryptocurrency oversight in the United States. With the landscape shifting rapidly, regulators face a growing dilemma: how to effectively oversee a decentralized financial ecosystem while respecting the privacy rights of individuals.
The Privacy vs. Security Debate
The crux of the issue lies in the fundamental differences between traditional banking systems and cryptocurrency networks. While banks are required to know their customers and report suspicious activities, cryptocurrencies operate on a fundamentally different model. Public blockchains allow for transactions to be recorded without revealing the identities of the parties involved, creating a tension between the desire for security and the right to privacy.
As the debate continues, several key points emerge:
- Identity and Anonymity: Unlike traditional financial systems, cryptocurrencies allow users to transact without disclosing their identities. This feature is often championed as a means of personal freedom but is also viewed as a potential loophole for illicit activities.
- Regulatory Overreach Concerns: Advocates for privacy argue that excessive regulation could push users away from regulated entities toward less secure platforms, ultimately undermining the very goals of the proposed rules.
- Innovation vs. Regulation: Striking a balance between fostering innovation in the crypto space and ensuring adequate protections against fraud and crime remains an ongoing challenge for regulators.
The Future of Crypto Regulation
As we look to the future, it is crucial for regulators to engage with the crypto community to develop frameworks that address both security and privacy concerns. This involves:
- Stakeholder Engagement: Ongoing dialogue between regulators, industry players, and privacy advocates can lead to more nuanced regulations that consider the unique aspects of cryptocurrency.
- Flexible Regulatory Approaches: Adapting regulations to accommodate the evolving nature of digital assets can ensure that frameworks remain relevant and effective.
- Technological Solutions: Leveraging technology to enhance transparency while preserving user privacy could provide a viable path forward.
Emerging Regulatory Trends: New Challenges Ahead
As the dust settles on the withdrawal of the 2020 proposal, new regulatory initiatives are already emerging. In October 2023, FinCEN opened a new proceeding focused on crypto mixing—a technique used to obfuscate the movement of funds on blockchain networks. While this development highlights ongoing concerns over illicit activities, it also raises critical questions about user privacy.
Understanding Crypto Mixing
Crypto mixing services allow users to combine their cryptocurrencies with others, effectively masking the trail of transactions. While this can serve legitimate privacy needs, it also poses challenges for law enforcement attempting to track illicit funds.
- Legitimate Use Cases: Many individuals and businesses value privacy in their financial transactions and may use mixing services to protect sensitive information from competitors or prying eyes.
- Regulatory Scrutiny: Regulators are tasked with distinguishing between legitimate privacy practices and those used to facilitate crime, creating a complex legal landscape.
Conclusion: Navigating the Future of Crypto Privacy
The evolution of cryptocurrency regulation in the U.S. reflects broader societal debates about privacy, security, and the role of government in overseeing emerging technologies. As the landscape continues to shift, the challenge for regulators will be finding a balance that protects individuals while addressing legitimate security concerns.
The journey of the proposed crypto privacy regulations illustrates the complexities of this endeavor. With a renewed focus on dialogue and innovation, there is hope for a regulatory framework that respects the ethos of cryptocurrency while ensuring a secure financial environment for all stakeholders. As we move toward an increasingly digital future, the lessons learned from this regulatory tug-of-war will shape the narrative of cryptocurrency and privacy for years to come.
No comments yet. Be the first to share your thoughts!